The Basis Point
The Basis Point delivers concise, timely insights on private credit from ZCG’s Credit team, focused on market dynamics, structural trends, and emerging risks shaping the lending landscape.
Each edition distills complex developments into clear perspectives that highlight dislocations, frame risk, and inform lenders and investors.
No items found.
No items found.

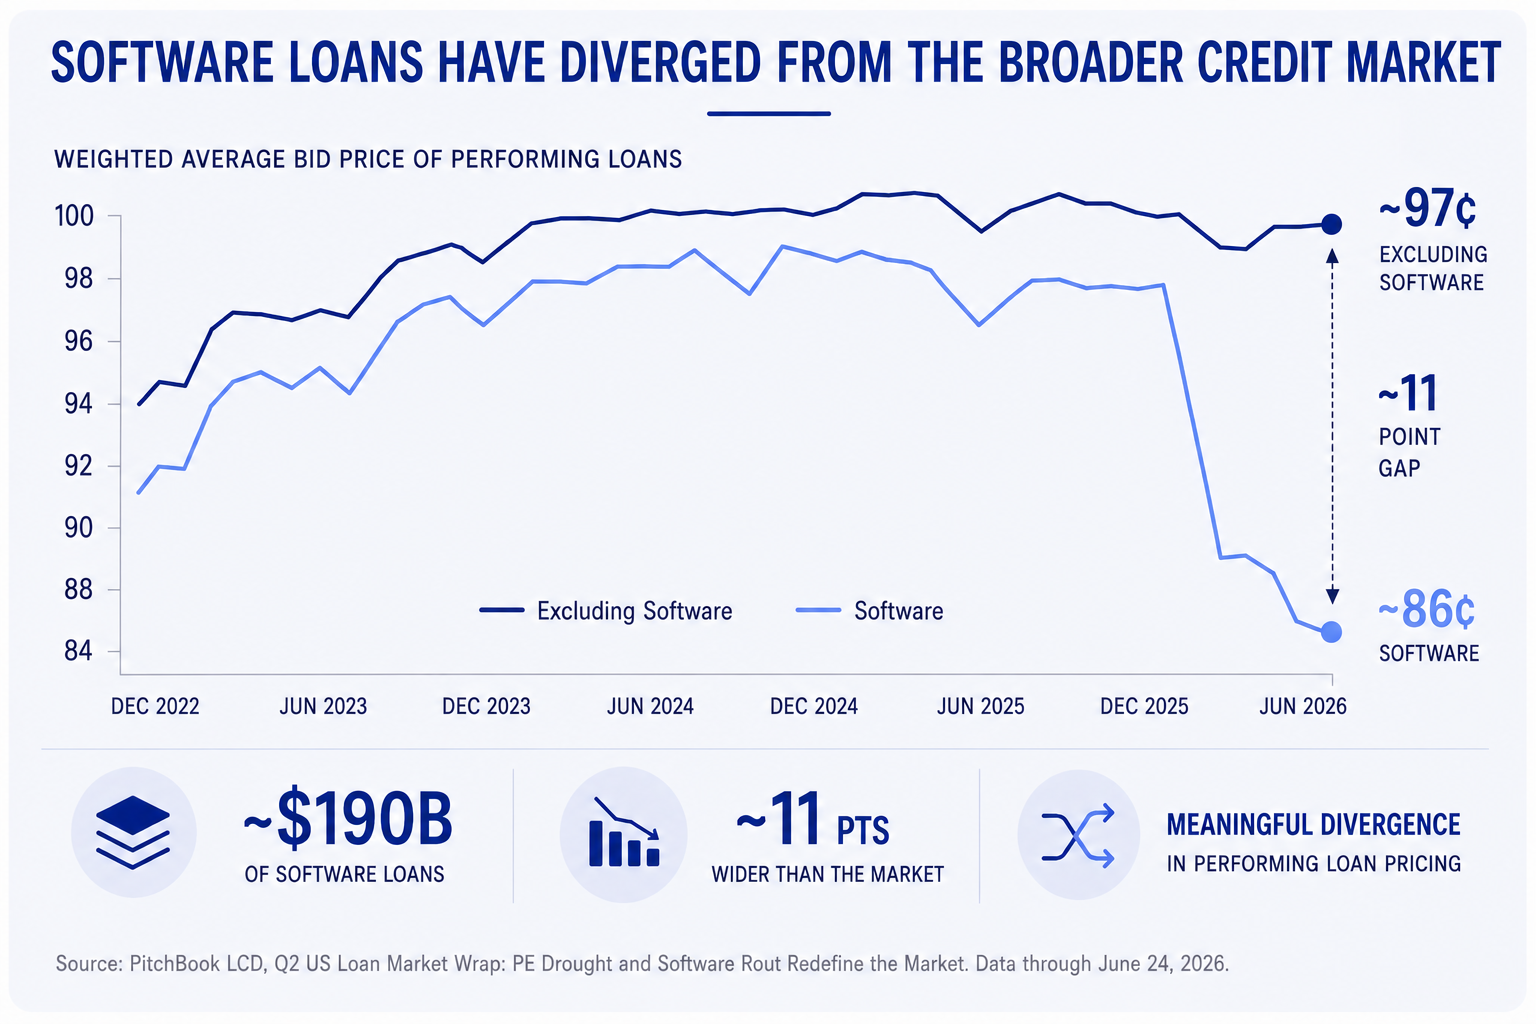
Takeaway: Software loan pricing decoupled sharply from the broader market over the first half of 2026. This looks like indiscriminate, sector-wide de-risking rather than company-by-company analysis.
Some borrowers certainly deserve to trade at stressed levels, but healthy credits were caught in the crossfire, giving bottom-up credit investors room to separate real balance sheet risk from simple collateral damage.
Credit Performance
No items found.
Aug 11, 2026
The Market Looks Resilient. The Borrowers Don’t
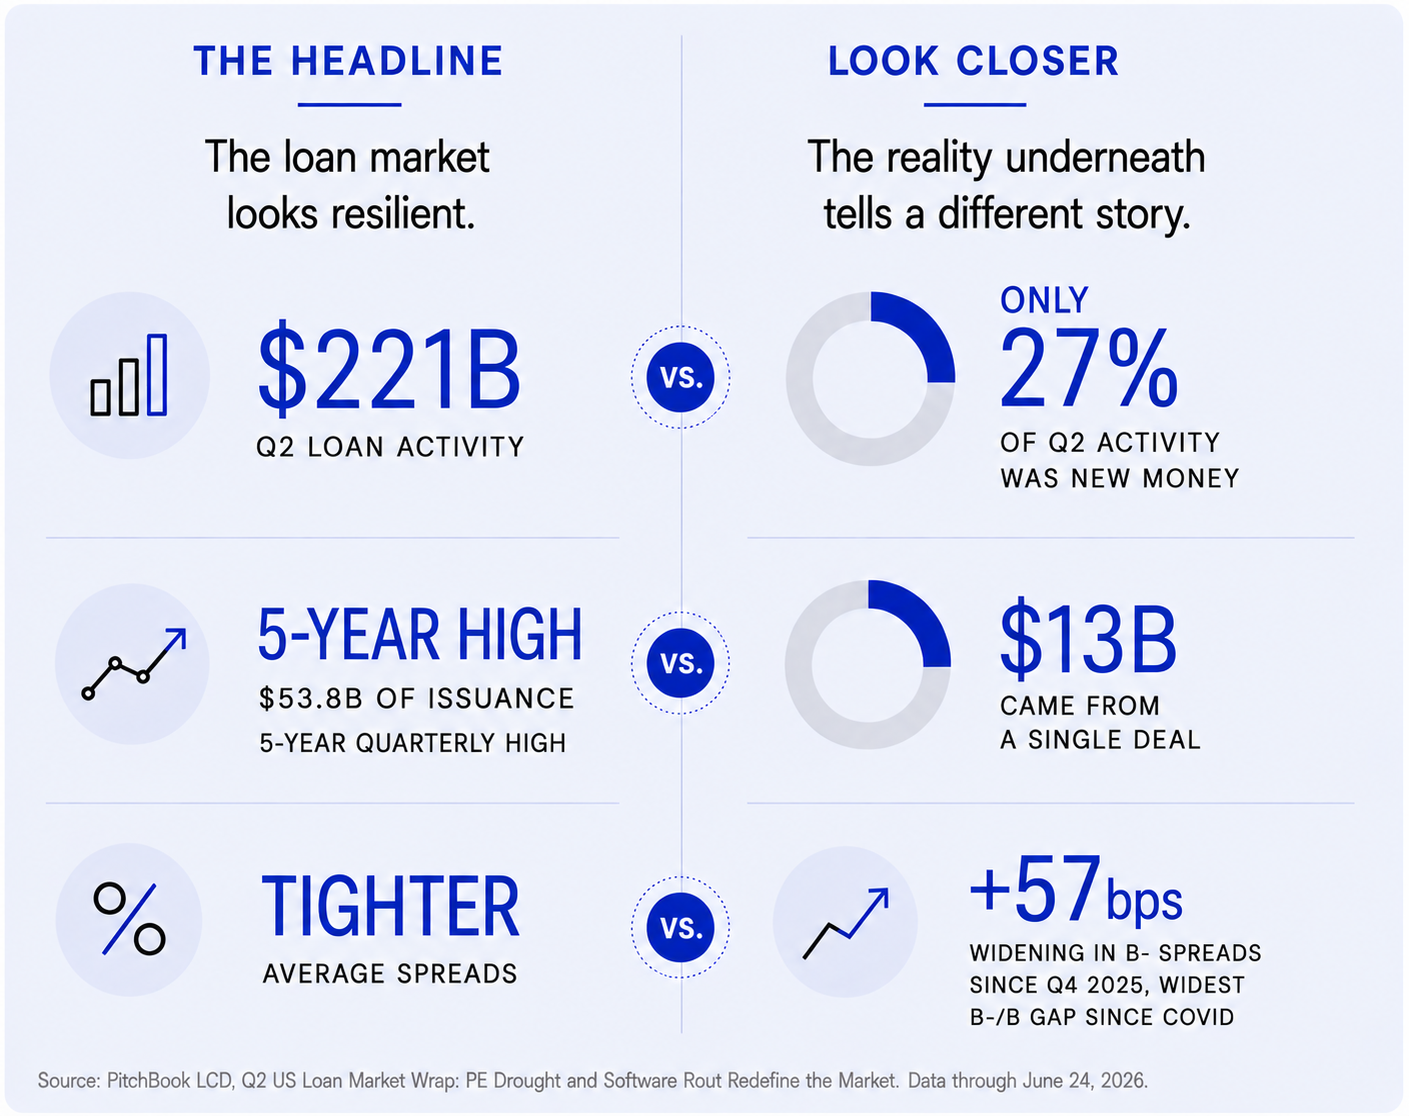
Takeaway: New money accounted for only ~27% of the $221B in Q2 loan activity, and of the $53.8B of issuance, a five-year high, $13B came from a single transaction. Borrowers are pushing out maturities rather than putting money to work.
The average spread looks steady, but B- paper has widened 57bps since Q4 2025 and now trades at its widest gap to single B since Covid. The average is holding because the dispersion is sitting inside it.
Liquidity & Refinancing
No items found.
Aug 5, 2026
Software's Primary Market Has Closed
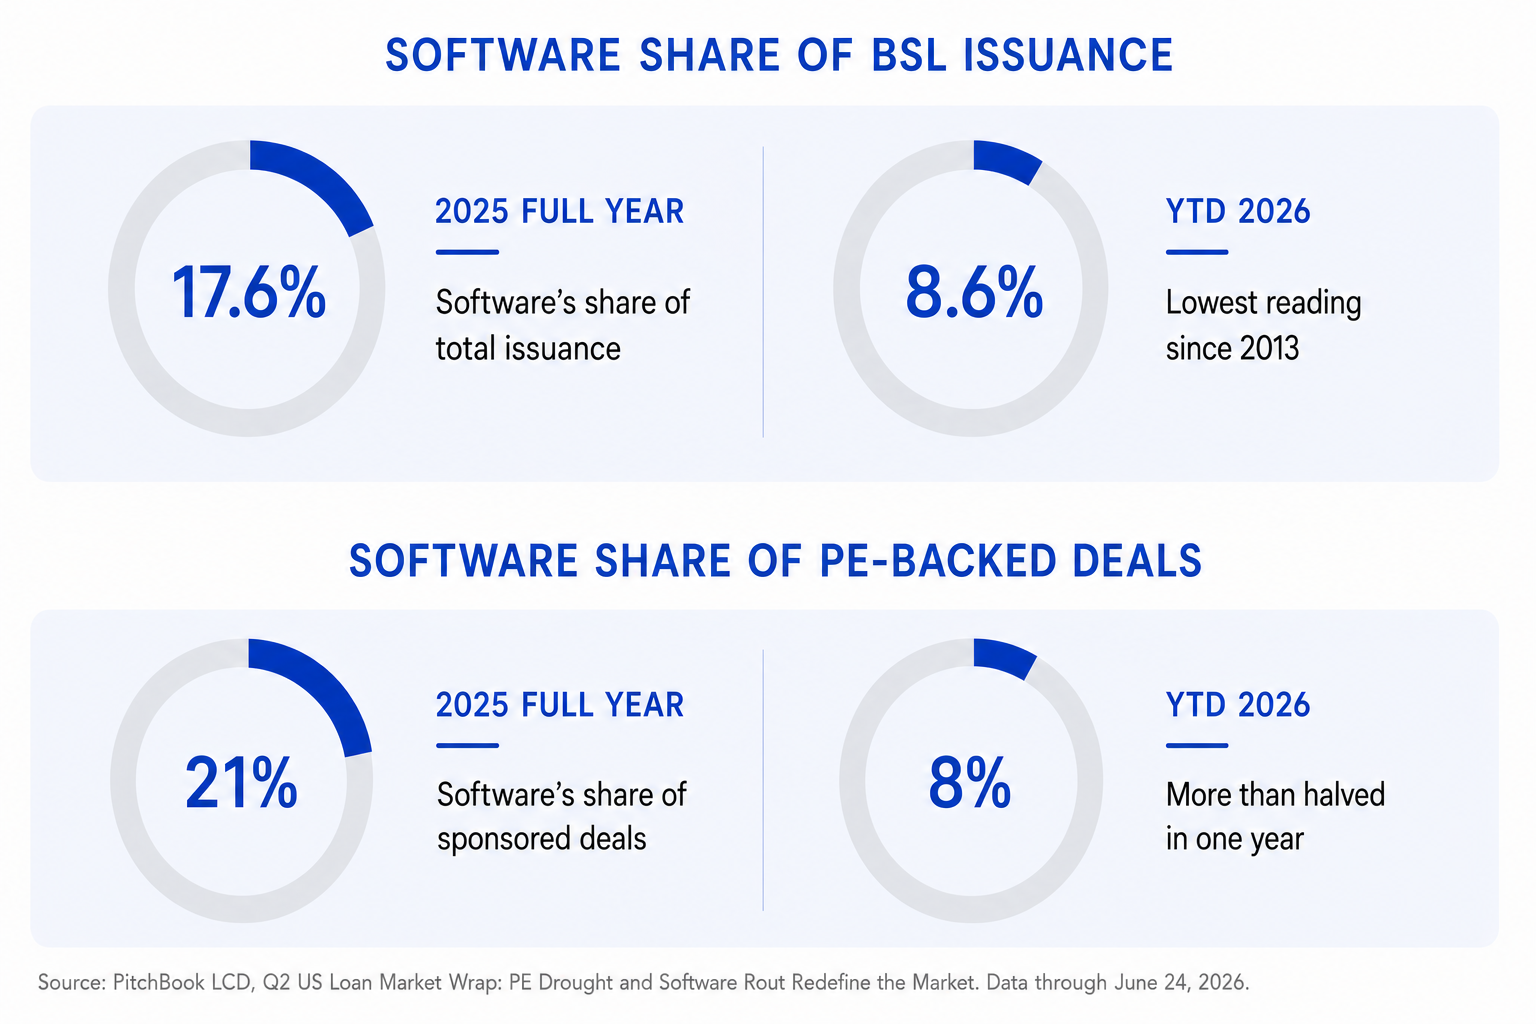
Takeaway: Software's share of new-issue BSL has fallen to 8.6% YTD, the lowest reading since 2013, and PE-backed software issuance has more than halved in a year.
Only 5% of software's $408B 2028 maturity wall has cleared to date, versus 42% for the rest of the market. Lenders aren't repricing software risk. They've stopped underwriting it.
Credit Performance
No items found.
Jun 22, 2026
Direct Lending Can't Handle an 8% Default Wave

Takeaway: At an 8% default rate, the direct lending market will have ~3,800 individual loans requiring restructuring. To put this operational burden into perspective, the entire institutional BSL market consists of only ~1,300 issuers. Direct lending is structurally unequipped to handle this volume.
There is no liquid secondary market to bring in distressed buyers or allow original lenders to exit, and no standardized documentation to accelerate negotiations.
The market faces a severe capacity crisis, a wave of ~3,800 highly bespoke, labor-intensive restructurings will utterly overwhelm fund managers, leading to prolonged asset paralysis and severely degraded recoveries.
Credit Performance
No items found.
May 4, 2026
PIK – the Silent Stress Indicator

Takeaway: BDC PIK income reached nearly 10% in Q4 2025, exceeding its COVID-era peak, highlighting increased reliance on non-cash interest, often consistent with rising borrower liquidity pressure.
Lenders and borrowers are increasingly relying on PIK interest to preserve the optics of performing loans while quietly compounding risk.
Credit Performance
No items found.
Apr 28, 2026
Recovery Rates are Collapsing

Takeaway: When defaults do happen, lenders are recovering far less than historical norms.
The real risk in private credit isn't just whether borrowers default, it's what you get back when they do.